
 SM
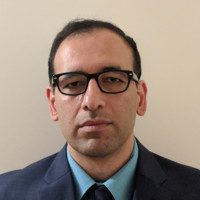
Shahriar Mokhtari Sharghi
 New York, New York, United States · operator
Shahriar Mokhtari Sharghi is an Iranian-born mathematician and quantitative-finance professional based in the New York area. He represented the Islamic Republic of Iran at the 1989 International Mathematical Olympiad, winning a Bronze medal, and earned a Ph.D. in Mathematics from Columbia University in 1998 (dissertation on spectral decomposition of tree lattices, advisor Hyman Bass). He was Associate Professor of Mathematics at Long Island University from 1998 to 2011, then moved into quantitative risk, serving as Risk Analyst Lead in Model Risk Management at AIG (2011-2017) and as VP, Senior Quantitative Financial Analyst at Bank of America (2017-2021). Since 2021 he has been a Director in Bank of America's Enterprise Risk Analytics group. The employment history is drawn from his LinkedIn profile record.

- Quant employment verification: CONFIRMED. LinkedIn enrichment lists an actual quantitative-finance role: VP, Senior Quantitative Financial Analyst at Bank of America (2017-06 to 2021-02), followed by Director, Enterprise Risk Analytics at Bank of America (2021-present). Bank of America is a global bank with a large quantitative risk/financial-analytics function, so this is genuine quant-finance employment, not a student program or competition. Identity is supported by the same record's 13-year mathematics faculty history at Long Island University (1998-2011), which matches the Columbia PhD mathematician (PhD 1998) who was the IMO 1989 Iranian contestant of the same name. Caveat: the employment evidence is the LinkedIn profile record (self-reported), retrieved via an index/enrichment; no independent primary-source page (company page, press, or filing) was found that separately confirms the Bank of America role, so treat the employment detail as LinkedIn-only.
- Identity caveat: no single primary source explicitly links the IMO 1989 contestant, the Columbia/LIU mathematician, and the Bank of America quant. The link rests on the exact name plus a coherent math-career trajectory (Columbia PhD 1998 -> LIU math faculty 1998-2011 -> quant risk roles); the LinkedIn record is the only source that carries the employment history.
- Earned a Ph.D. in Mathematics from Columbia University in 1998; dissertation 'On Spectral Decomposition of Tree Lattices', advisor Hyman Bass. This is the mathematics-doctorate anchor that connects the Iranian olympiad name to the later quant career.1998
- Career timeline is a single continuous math-to-finance track: LIU mathematics faculty 1998-2011, AIG model-risk model validation 2011-2017, Bank of America quantitative analyst 2017-2021, Bank of America Director (Enterprise Risk Analytics) 2021-present, all in the New York area.
- Worked as Risk Analyst Lead, Model Risk Management at AIG (New York) from 2011 to 2017, described as model validation within Enterprise Risk Management, a quantitative risk role at a global insurer.2011
- Served as Associate Professor of Mathematics at Long Island University from 1998 to 2011, doing research and teaching in mathematics, computer science and statistics, before moving into quantitative finance at AIG in 2011.1998
- Won a Bronze medal at the 30th IMO (1989) representing the Islamic Republic of Iran, ranked 129th with 20 points (P1=2, P2=7, P3=0, P4=0, P5=7, P6=4). This is the olympiad identity the task named, confirmed by the official IMO results table.1989
- Academic output centers on tree lattices and spectral graph theory: publications include 'Ramanujan Edge-Indexed Graphs' (J. Combin. Theory B, 2001), 'Cheeger Inequality for Infinite Graphs' (Geometriae Dedicata, 2003), and work on zeta functions of discrete groups acting on trees. ResearchGate lists 6 items with 69 citations.
Developer, Enterprise Risk Analytics
Model Validation within Enterprise Risk Management
Research and teaching in Mathematics, Computer Science and Statistics
Developer, Enterprise Risk Analytics
Model Validation within Enterprise Risk Management
Research and teaching in Mathematics, Computer science and Statistics
Competition record
Islamic Republic of Iran · IMO